A reported gas-generator transaction brings AI’s physical costs into focus. It is not a disclosed electricity tariff—or proof that households will pay.
By Energy News Beat | As of November 8, 2026 CST
The important word is generators
When an AI company makes a multibillion-dollar power move, families have a reasonable question: does this help keep the lights on, or leave us paying for somebody else’s expansion? Anthropic’s reported transaction deserves attention. But the first distinction matters: buying equipment to generate electricity is not the same thing as signing a retail power contract, and neither tells us what a household will pay.
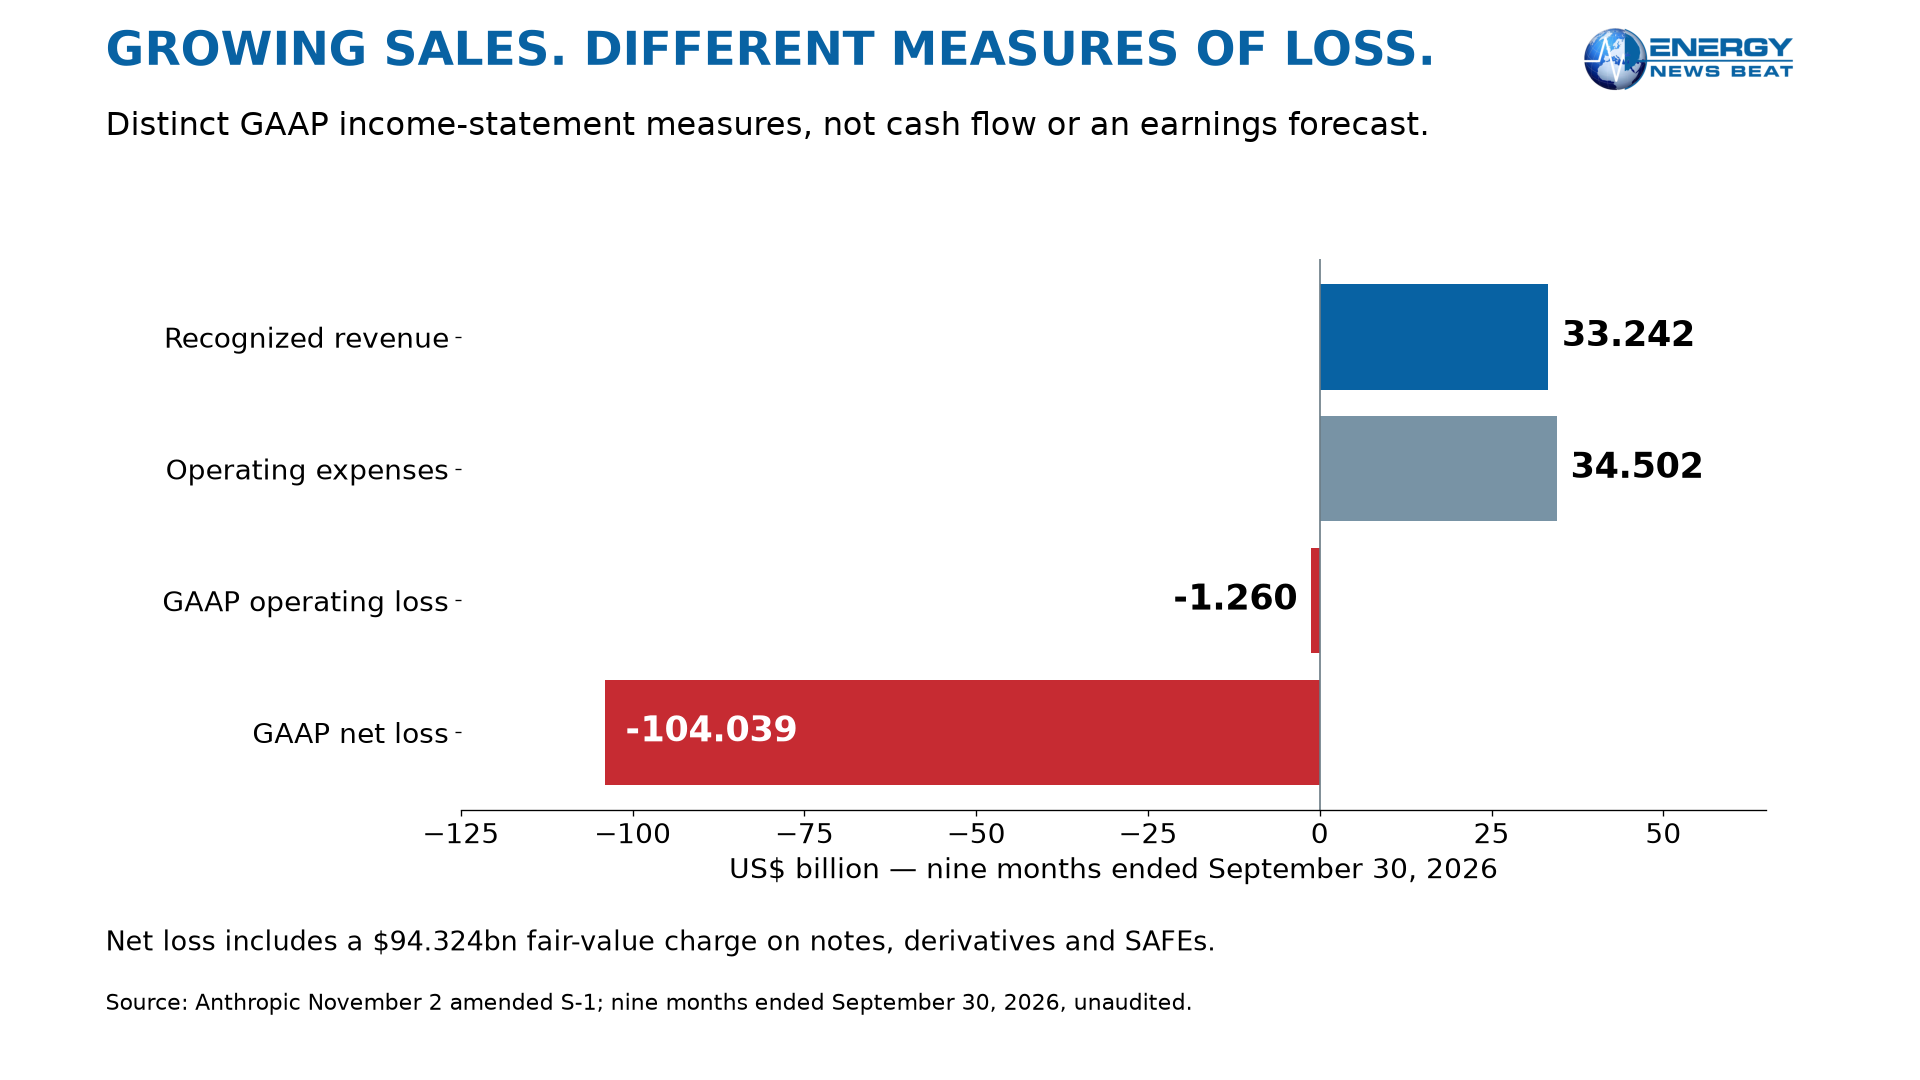
On November 8, Reuters reported that the Financial Times said Anthropic had bought commitments for 1.7 gigawatts of heavy-duty gas-fired generators from San Antonio-based OnePWR Solutions in late September, in a deal worth about $3.4 billion. Engineering and construction capabilities needed to install the generators were included. Reuters explicitly said it could not immediately verify the report; Anthropic and OnePWR had not responded to its requests for comment. Reuters via CNA.
Separately, transaction adviser Piper Sandler lists OnePWR Solutions (CK Holdings Group, LLC), a September 2026 transaction valued at $3.4 billion, and the sale of its power-generation platform to an unnamed ‘frontier AI lab.’ The seller, month and rounded value are consistent with the reporting, but the summary does not identify Anthropic or establish the precise assets, contracts or legal entities transferred. Without the agreement, it should not be treated as independent confirmation of the reported equipment-order takeover’s exact scope. Piper Sandler.
The distinction also rules out a tempting shortcut. Reuters’s account says Anthropic did not acquire OnePWR itself and no employees transferred. We should not describe this as a corporate takeover or a $3.4 billion purchase of electricity over a specified contract term. A cash-payment schedule, financing package, electricity price and delivery timetable have not been established by the accessible primary transaction summary.
Capacity on order is not power at the socket
One gigawatt is 1,000 megawatts, so the reported equipment commitments total 1,700 MW. That is rated power, not electricity already delivered. Dividing the rounded reported price by that capacity gives about $2,000 per kilowatt. It is a transaction-scope ratio, not a complete power-plant construction benchmark, a fuel-inclusive electricity price or a forecast of household bills.
Investing.com’s separate FT-attributed account says OnePWR had ordered the generators from Caterpillar roughly two years earlier and needed financing, with Anthropic taking over existing orders. This is useful reporting, but the adviser’s summary does not independently establish those details. An order transfer must not automatically be booked by readers as a fresh $3.4 billion addition to Caterpillar’s backlog. Investing.com.
Nor does securing existing equipment orders mean existing electricity has been diverted from homes. New installations could add generation, but locations, permits, interconnection arrangements, fuel supply and commissioning still determine what actually operates. The accessible primary summary does not identify the generating sites. San Antonio is the supplier’s reported home, not proof of a Texas data-center location. Claims of operating capacity, a particular utility footprint or an entirely off-grid system would get ahead of the evidence.
Anthropic has financial statements—not just a revenue headline
The financial story has changed from the familiar private-startup shorthand. Anthropic announced an S-1 filing on October 26 for a proposed Nasdaq listing under ANT. The announcement said the registration was not yet effective; the preliminary prospectus says there had been no public market. The November 2 S-1 amendment remains a preliminary prospectus with no public market before the offering. Those records establish an IPO proposal, not a completed flotation or an available trading recommendation. A proposed symbol is not proof of a live listing. Company announcement; November 2 amended S-1.
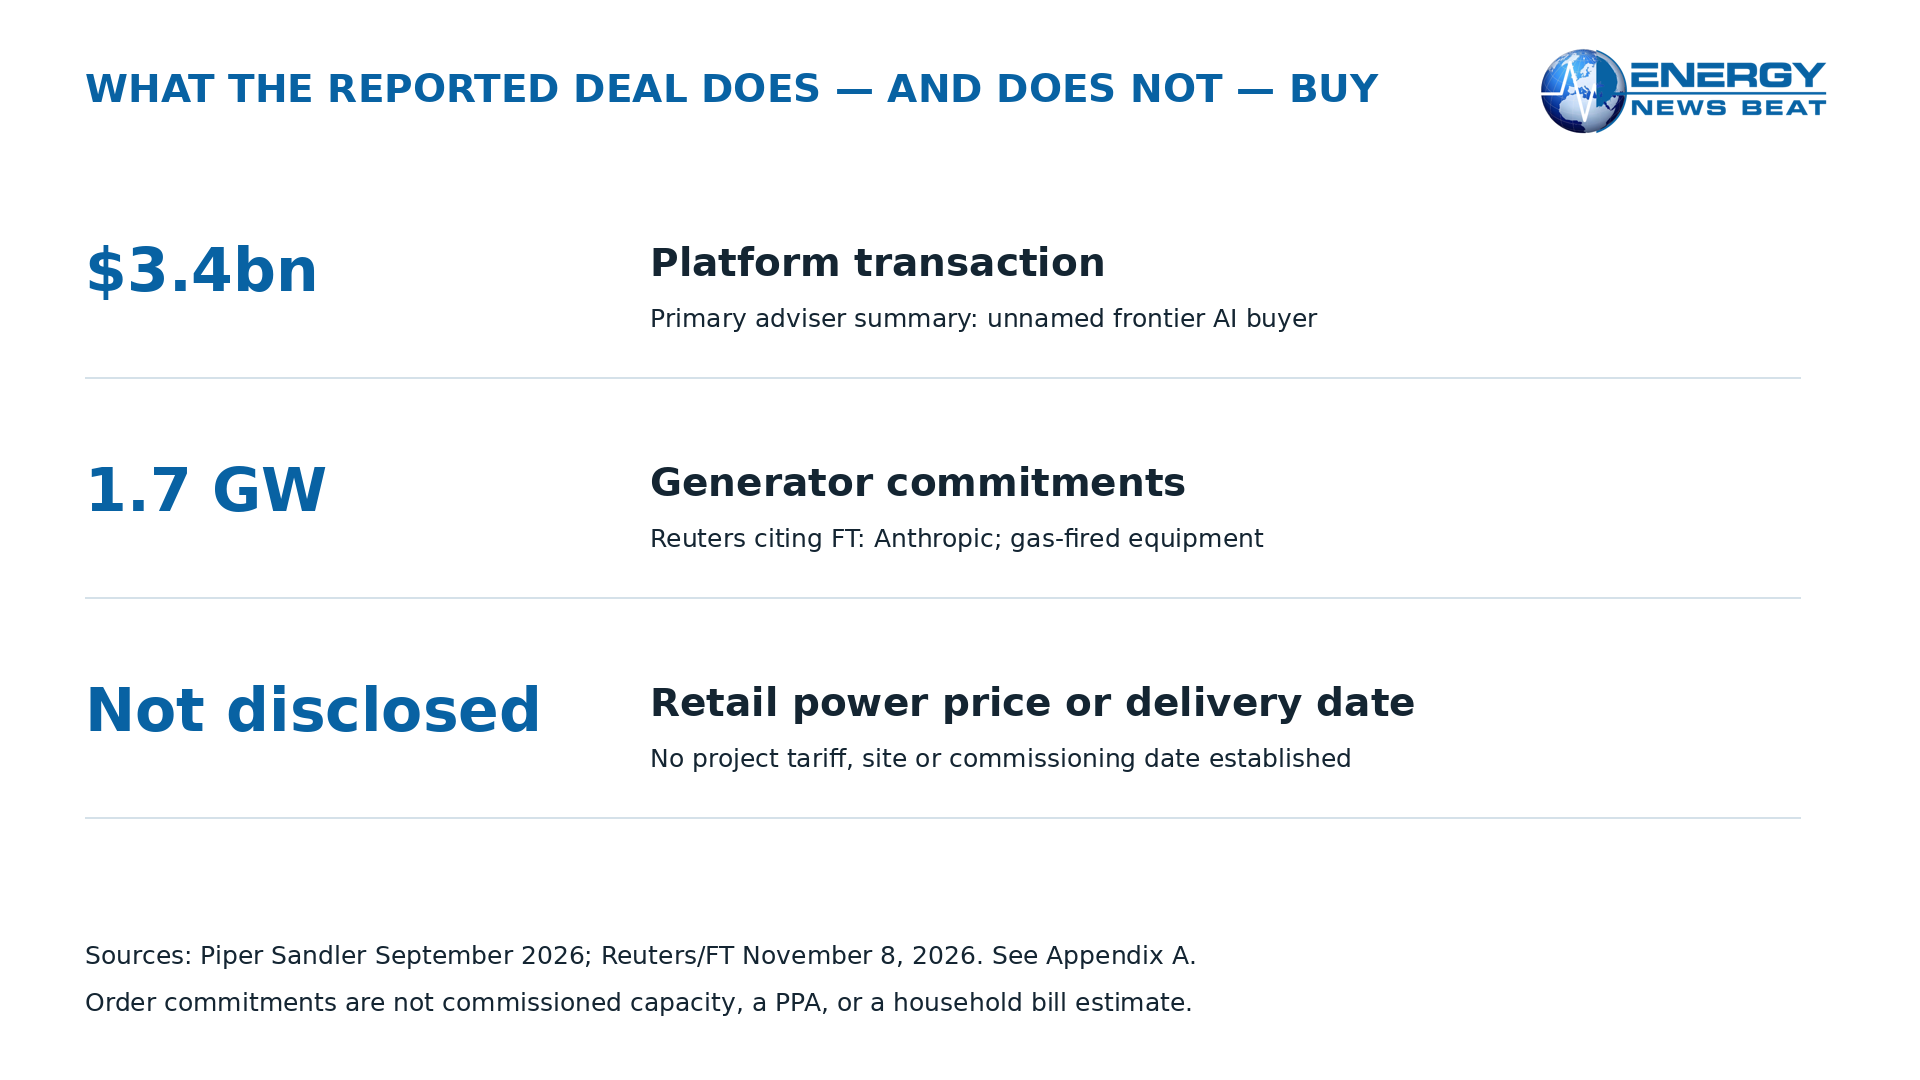
The November 2 amendment reports $33.242 billion of recognized revenue for the nine months ended September 30, 2026, compared with $2.545 billion in the corresponding 2025 period. The 2026 interim figures are unaudited. GAAP operating loss was $1.260 billion; GAAP net loss was $104.039 billion. These are real disclosed financial measures, but they describe different things—and none is a new November quarterly earnings release.
The nine-month net loss includes a $94.324 billion fair-value charge on convertible notes, derivative liabilities and SAFEs. That accounting charge must not be called an equivalent cash burn. For historical cash-flow context, the original October 26 filing reported $3.929 billion of operating cash inflow in the first half—not the nine-month period. Neither that earlier inflow nor a noncash loss adjustment erases capital spending, financing dependence or future contractual obligations. The amendment reports approximately $895.4 billion of committed spend as of and subsequent to September 30, substantially all for compute and infrastructure, including about $69.8 billion due in the following twelve months.
In May, Anthropic announced $65 billion of Series H funding at a $965 billion post-money valuation and said run-rate revenue had crossed $47 billion earlier that month. Funding is not sales; valuation is not cash; annualized run-rate is not recognized full-year revenue. The S-1 defines run-rate using trailing 28-day consumption fees multiplied by 13 plus monthly subscription fees multiplied by 12. Mixing that snapshot with a nine-month income statement would create a misleading growth comparison. May 28 funding announcement.
For families, the protection is in the paperwork
Privately funded generation can be constructive if it adds dependable supply and its owner pays the associated costs. It can also leave public costs if grid connections, backup service, gas infrastructure or network upgrades are allocated to others. Without project locations and service agreements, neither an automatic rate increase nor automatic savings can responsibly be attached to this transaction.
For each eventual project, the useful questions are concrete: who pays for substations and transmission, and who pays when the plant is unavailable? Does the tariff charge for backup capacity even when grid electricity use is low? Are minimum payments enforceable, supported by collateral or a parent guarantee, and long enough to recover dedicated infrastructure costs? What exit payment applies if computing demand moves elsewhere? These are evaluation criteria, not disclosed OnePWR deal provisions.
Fuel and reliability deserve the same discipline. Gas-fired equipment needs dependable fuel, maintenance, permits and an operating plan. Generation sitting near a data center does not automatically remove all grid costs or make all of its capacity available to neighbors. Community benefits should be demonstrated through actual infrastructure and cost-allocation records, not assumed from the size of the announcement.
For investors, demand is only half the story
The opportunity is straightforward: reliable electricity can help turn computing demand into a service customers can actually use. The risk is equally physical. Equipment delivery, installation, fuel availability and financing must line up with occupied data centers and paying customers. Faster AI revenue growth does not guarantee that every infrastructure commitment earns an attractive return.
Caterpillar is a reported equipment connection here, not a primary-confirmed new-order windfall. Anthropic’s proposed IPO deserves scrutiny of the current prospectus, governance, obligations and final pricing rather than a purchase based on a proposed ticker. Investors assessing suppliers or financing partners should establish the actual contract, payment security and exposure size. The sensible conclusion is not that AI power is good or bad by definition: it is that signed obligations and who bears the downside matter more than the headline.
Stu’s Take
I want America to build the power infrastructure that lets businesses grow without making families the backstop for somebody else’s business plan. Anthropic’s reported generator move points to a practical reality: an AI service still needs machines, fuel, construction crews and dependable electricity.
But let’s keep the accounting and the electric bill honest. A reported $3.4 billion equipment transaction is not a disclosed power price. A huge fair-value accounting loss is not the same as cash leaving the bank, and a fast-growing revenue run-rate is not a year of booked sales.
My test is simple: bring credible financing, pay the infrastructure and backup-service costs you cause, and protect other customers if the project shrinks or leaves. If those protections are real, new private investment can be welcome. If they are missing, the size of the AI promise should not excuse shifting the risk to the kitchen-table budget.
Appendix A | Transaction terms and unresolved scope
| Term | Evidence and limit |
| Value / status | $3.4bn September 2026 platform sale in adviser summary; roughly $3.4bn late-September generator commitments per Bloomberg/Reuters citing FT. Matching seller, month and rounded value do not establish identical contractual scope. |
| Seller identity | Adviser heading: OnePWR Solutions (CK Holdings Group, LLC). No purchase agreement reviewed. The agreement has not established the definitive legal selling entity. |
| Buyer | Unnamed frontier AI lab in primary adviser record; Anthropic identified by FT as relayed by Bloomberg/Reuters. Exact purchasing subsidiary unestablished. |
| Scope | Platform sale per adviser; generator-order takeover per Bloomberg/FT, with engineering/construction capability per Reuters/FT. Exact contractual perimeter not matched to an executed agreement. No company acquisition or employee transfer per reporting. |
| Capacity / source | 1.7GW heavy-duty gas-fired generators, reported. Existing Caterpillar orders per Investing.com citing FT; primary manufacturer confirmation unavailable. |
| Location / schedule | San Antonio is reported supplier base. Installation sites, permits, in-service dates, generation duty, fuel pipeline and grid arrangements not established. |
| Financing / price | No primary payment schedule, cash/equity split, prepayment amount, debt terms or power-purchase term available. No disclosed electricity price. |
| New generation | Equipment-order transfer is not proof of operating generation, commissioning, increased manufacturer backlog or allocation of existing grid supply. |
| Consumer provisions | No project tariff, minimum-take/pay obligation, exit collateral, parent guarantee or transmission cost-allocation record identified. No modeled household impact. |
| Arithmetic | US$3.4bn / 1.7GW = $2bn/GW = $2m/MW = $2,000/kW. Rounded reported values; includes broader reported scope; not LCOE or EPC-only benchmark. |
Primary summary: Piper Sandler. Reporting: Bloomberg, Reuters via CNA and Investing.com.
Appendix B | Financial metrics: keep the denominators separate
| Metric (US$ billion) | Period / value | Classification |
| Recognized revenue | 9M 2025: 2.545; 9M 2026: 33.242 | GAAP income statement; interim unaudited |
| Operating expenses | 9M 2026: 34.502 | GAAP; includes compute and infrastructure 18.808 |
| Operating loss | 9M 2026: -1.260 | GAAP; 33.242 – 34.502 |
| Net loss | 9M 2026: -104.039 | GAAP; not operating loss or cash flow |
| Fair-value charge | 9M 2026: 94.324 expense | Convertible notes, derivative liabilities and SAFEs; noncash reconciliation item |
| Other income/expense, net | 9M 2026: -10.397 | Separate income-statement row; not solely the convertible-note charge |
| Operating cash flow | H1 2025: -1.513; H1 2026: +3.929 | Cash-flow statement; not net income |
| Investing cash flow | H1 2026: -17.181 | Includes securities transactions, not all capex |
| Purchases of property/equipment | H1 2026: 0.482 outflow | Cash-flow statement; do not label all investing outflow construction |
| Cash/equivalents + short-term investments | September 30, 2026: 131.845 | Amended S-1 balance-sheet stock, not November cash |
| Committed spend | As of/subsequent to September 30: ~895.4; next 12 months ~69.8 | Purchase/lease commitments, substantially compute/infrastructure; not all debt or near-term cash |
| Run-rate revenue | Crossed 47 in May 2026 | Annualized operating metric; NOT recognized FY revenue |
| Series H raised / post-money value | May 28: 65 / 965 | Funding / equity valuation, not operating revenue |
Sources: November 2 amended S-1 for nine-month/current balance-sheet and commitment figures; October 26 Form S-1; May 28 Series H announcement. S-1 summary reports annual 2023–2025 data derived from audited statements and interim data from unaudited statements. Historical H1 cash-flow rows deliberately retain their original six-month periods; they are not latest nine-month cash-flow totals. These are historical prospectus figures, not a November quarterly earnings release or a full-year 2026 forecast.
Company definition: Run-Rate Revenue = trailing 28-day consumption-based fees × 13 + monthly subscription fees × 12. The definition is not a commitment that the next twelve months will produce that amount. No run-rate/recognized-revenue ratio or cash-runway model is presented.
Appendix C | Consumer and investor diligence
Consumer analysis is conditional, not a finding about any named tariff: identify the utility and jurisdiction; obtain the approved service agreement and cost-of-service record; trace generation, gas connection, transmission and distribution costs separately.
Check reserved capacity and backup-service charges, minimum payments, credit support, termination amounts, cost-recovery term and treatment of unused assets. Match the obligation to the legal entity and enforceable guarantee, not merely a parent brand.
For investors: distinguish reported equipment provenance from a manufacturer award, backlog addition or recognized revenue. Establish delivery milestones, cancellation rights, payment security, fuel exposure, financing and customer concentration before assigning upside.
IPO status here rests on the October 26 announcement and November 2 preliminary amended S-1. The reviewed records establish a proposed IPO, not a completed offering or live ANT trading.
No statewide rate comparison, household bill estimate, political causal inference, emissions model, utilization assumption or speculative supplier recommendation is included. The deal’s undisclosed sites prevent a responsible project-specific ratepayer calculation.
Appendix D | Linked source ledger and selected evidence
Access date: November 8, 2026 CST. Selected excerpts are short evidence pointers, not full reproductions. Failure to fetch an original is an access gap, not proof that it does not exist.
01. Reuters via CNA, November 8, 2026
Selected excerpt: “Reuters could not immediately verify the report”.
FT-attributed reporting; buyer/capacity and no employee transfer are reported, not operator-confirmed.
02. Piper Sandler transaction summary, September 2026
Selected excerpt: “sale of its power generation platform to a frontier AI lab”.
Primary adviser record: $3.4 billion; OnePWR Solutions (CK Holdings Group, LLC). Buyer unnamed, no capacity or price per MWh. Its platform-sale perimeter has not been matched to the reported generator-order takeover through an executed agreement.
https://www.pipersandler.com/investment-banking-transactions/onepwr-solutions-20260901
03. Anthropic, PBC amended Form S-1, filed November 2, 2026
Selected excerpt: “Revenue | $41 | $386 | $4,585 | $2,545 | $33,242”.
Figures come from the prospectus’s consolidated financial tables and commitment disclosures. Nine-month 2026 interim results are unaudited; the prospectus is preliminary, not a completed IPO.
https://www.sec.gov/Archives/edgar/data/2130357/000162828026068676/anthropicpbc-sx1ax1.htm
04. Anthropic, PBC Form S-1, filed October 26, 2026
Selected excerpt: “Prior to this offering, there has been no public market for our Class A common stock”.
Historical cash-flow figures come from the prospectus’s consolidated cash-flow tables and MD&A. Interim six-month 2026 results are unaudited and retain their labeled period.
https://www.sec.gov/Archives/edgar/data/2130357/000162828026067168/anthropicpbc-sx1.htm
05. Anthropic Series H announcement, May 28, 2026
Selected excerpt: “our run-rate revenue crossed $47 billion earlier this month”.
$65bn raised includes $15bn of previously committed hyperscaler investments, not an additional $15bn on top of the round.
https://www.anthropic.com/news/series-h
06. Anthropic proposed IPO announcement, October 26, 2026
Selected excerpt: “has not yet become effective”.
Planned ANT listing, not a completed listing. The reviewed records establish a proposed IPO, not live trading.
https://www.anthropic.com/news/s1-sec
07. Investing.com, Jaiveer Shekhawat, November 8, 2026
Selected excerpt: “OnePWR had ordered the generators from Caterpillar about two years ago”.
FT-attributed equipment/order mechanics, not independent manufacturer confirmation. No primary Caterpillar order announcement underpins the supplier discussion.
08. Bloomberg, Eleanor Thornber, November 8, 2026, 5:48 AM CST
Selected excerpt: “without acquiring the company itself, according to the newspaper”.
The complete two-paragraph report was reviewed in a separate editorial browser check. It attributes the commitments and takeover of existing Caterpillar orders to FT, not independent buyer or contractual-scope confirmation. It supplies no site, tariff, financing or financial-statement terms.
09. Financial Times underlying article, November 8, 2026
Underlying article body unavailable for full-text review.
Underlying FT body remains unavailable for full-text review behind its subscription page. No unseen terms or original-body quotations are assumed.
https://www.ft.com/content/41bf5c6a-9735-4f1a-a8e3-2bcccad58ba0
Appendix E | Verification method and limitations
The adviser’s platform-sale description and the reported generator-order assignment are separate source descriptions; their exact contractual perimeter has not been matched to an executed agreement. Matching seller, month and rounded value do not independently identify the legal buyer or prove identical assets, contracts or company-acquisition scope.
Bloomberg’s short November 8 report, reviewed in a separate editorial browser check, attributes the generator commitments and takeover of existing Caterpillar orders entirely to the Financial Times and says Anthropic did not acquire OnePWR itself. The underlying FT article remains unavailable for full-text review. Bloomberg, Reuters and Investing.com are FT-dependent reports, not additional independent confirmation of the buyer or contract terms.
No executed acquisition agreement, equipment assignment, site permit, utility tariff, credit agreement or primary Caterpillar confirmation was reviewed. No full-text purchase terms or legal-entity chain inferred.
The cited financial figures come from the prospectus’s consolidated financial tables and commitment disclosures; interim results are unaudited, and periods differ where labeled. Financial reporting dates differ from the transaction date; September liquidity is not a current November balance.
Figures retain native US dollars. Billions are converted from filing millions by dividing by 1,000. Both charts use reported/primary figures without a forecast, invented utilization or electricity-price conversion.
Proposed Stu’s Take is opinion; no personal recollection or unsupported quotation is attributed to Stu.
The post Anthropic’s Reported $3.4 Billion Power Move: Read the Equipment Order Before the Electric Bill appeared first on Energy News Beat.