Japan is on track to reclaim the title of the world’s largest liquefied natural gas (LNG) importer in 2026 for the first time since 2022, narrowly ahead of China. Analysts at ICIS and Kpler both forecast a slim Japanese lead driven by weak Chinese spot buying amid high prices, full storage, and structural shifts toward cheaper alternatives, rather than any surge in Japanese demand.Reuters
ICIS projects Japan at 62 million metric tons (Mt) and China at 61 Mt for the full year. Kpler sees Japan at 63 Mt versus China at 62 Mt. China first took the top spot in 2021 after years of rapid growth, lost it briefly to Japan in 2022 amid COVID restrictions, and held it from 2023 through 2025. High LNG prices—exacerbated by the Middle East conflict and effective closure of the Strait of Hormuz disrupting Qatari and UAE shipments—have curbed Asian spot demand overall, with China’s pullback more pronounced. Chinese underground storage was already 80-90% full by the end of September, with some regions above historical levels, limiting the need for additional cargoes ahead of a potentially mild winter.Oilprice
China’s LNG Import Volumes and Suppliers
China’s LNG imports have fallen sharply from their 2021 peak of around 79 Mt. Full-year 2025 totals were roughly 66–69 Mt (IEEFA cites ~66 Mt; other trackers around 68.2–69.8 Mt), down from ~77–79 Mt in 2024 and the lowest since 2022 in some estimates. Early 2026 data show further softness: China imported 35.3 Mt in January–July, down 2.5% year-on-year and trailing Japan’s 37.3 Mt.Globallnghub
Approximate 2025 supplier breakdown (based on Chinese customs and trade data totaling ~69 Mt):
- Australia: ~20.6 Mt (still the top supplier despite declines in some periods)
- Qatar: ~19.6 Mt
- Russia: ~9.95 Mt (up ~18% year-on-year)
- Malaysia: ~7.2 Mt
- Indonesia: ~4.1 Mt
- Others (Papua New Guinea, Oman, Nigeria, UAE, Canada, Mozambique, etc.): the remainder, with U.S. volumes near zero for much of the year due to tariffs (only ~0.26 Mt recorded).
January–July 2026 source mix (35.3 Mt total, seaborne):
- Australia: 12.6 Mt (+6.3% y-o-y), ~35.6% share
- ASEAN (Malaysia, Indonesia, Brunei, Singapore): 7.1 Mt (+6.9%), ~20%
- Qatar: 4.7 Mt (−57.6%), ~13.3% (Hormuz disruption)
- Russia: 4.3 Mt (+31.3%), ~12.3%
- Canada: 1.4 Mt (new supplier, ~4%)
- United States: negligible (~0.1 Mt)
The supply mix has shifted toward Australia, Southeast Asia, Russia, and Canada as Qatari volumes collapsed and U.S. cargoes largely vanished.Globallnghub
Energy Mix and Coal’s Persistent Role
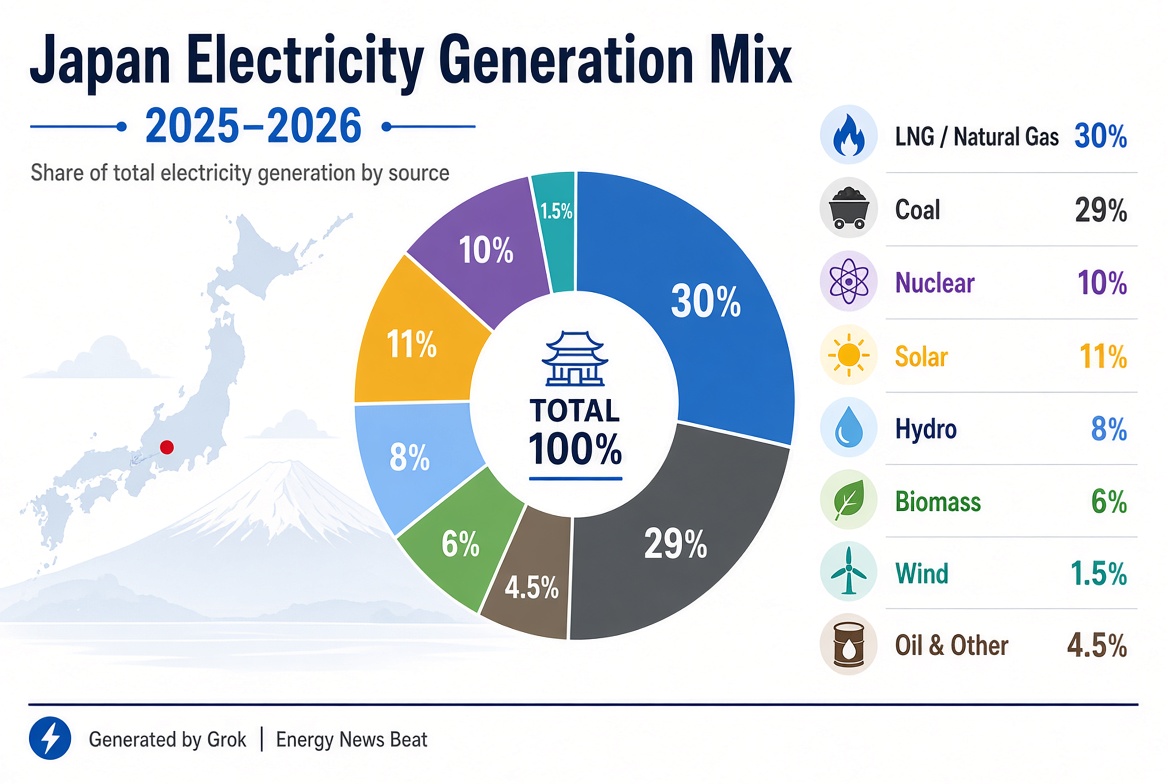
In 2025 China generated roughly 10,500 TWh of electricity. Coal still dominated at about 54–55%, followed by hydro (~13%), solar (~11%), wind (~11%), nuclear (~4.6%), and gas (~3%). Low-carbon sources (renewables plus nuclear) reached ~42%. Coal-fired generation fell for the first time since 2015 (down ~1–1.6% or 70–90 TWh in various tallies) even as overall demand rose ~5%, with renewables covering the growth. Wind and solar capacity surpassed coal’s installed capacity for the first time. Gas plays only a minor role in the power mix (~3%).Globalgrid
Despite the generation decline and falling utilization rates (around 47% in some assessments, well below historical levels), China continues aggressive coal capacity additions for energy security and system flexibility. In 2025, new and reactivated coal power proposals surged to a record 161 GW. The country commissioned ~78 GW of new coal capacity (the highest in a decade) and ended the year with ~291 GW in the pipeline (permitted or under construction). Some previously delayed or “retired” projects were reactivated amid post-2022 shortage concerns and a focus on dispatchable backup, even as clean energy growth reduces coal’s operating hours and risks overcapacity.Globalenergymonitor
Still Needing LNG—But Over-Contracted
China’s overall gas demand has held up better than LNG imports, supported by rising domestic production and pipeline gas (Power of Siberia from Russia and Central Asian volumes). LNG has been the swing supply and is price-sensitive. High spot prices have kept buyers on the sidelines, while the country has built a large long-term contract portfolio.
Between 2021 and 2023 Chinese buyers signed nearly 60 Mt of new supply agreements. Total contracted volumes are expected to reach 114 Mt by 2028, far above current and projected import needs (IEEFA sees 2026 imports around 63 Mt). This mismatch has turned China into a major reseller: IEEFA estimates 17–19 Mt resold in 2025 alone (including 8.4 Mt on Chinese-chartered vessels), with top destinations including South Korea, Japan, and the Netherlands. Chinese firms have earned billions from reselling flexible U.S. and Australian volumes, optimizing Pacific portfolios and capturing Atlantic arbitrage. Recent deals continue the pattern, such as China Gas’s new 0.5 Mt/year, 20-year SPA with Venture Global starting in 2030 (bringing its total with the firm to 2.5 Mt/year). Other 2025 agreements include volumes with BP, ADNOC, and others.Ieefa
The result is a structural surplus that could reach tens of millions of tons by the early 2030s if demand growth remains modest. Flexible FOB contracts, especially from Australia and the U.S., give Chinese buyers optionality to import when prices are attractive or redirect cargoes elsewhere. Combined with coal for reliability, domestic gas, pipelines, and rapid renewable buildout, this leaves LNG as a valuable but no longer dominant or rapidly growing component of China’s energy security toolkit.
Japan’s narrow 2026 edge is therefore more a story of Chinese restraint and diversification than Japanese expansion. Full-year final numbers will depend on winter weather and price movements, but the ranking shift underscores how quickly Asian LNG dynamics can change when one major buyer steps back.
Appendix: Sources and Links
- Reuters (30 Oct 2026): China set to lose LNG import crown to Japan on weak demand — https://www.reuters.com/business/energy/china-set-lose-lng-import-crown-japan-weak-demand-2026-10-30/
- OilPrice.com (30 Oct 2026): Japan to Overtake China As World’s Top LNG Importer This Year — https://oilprice.com/Latest-Energy-News/World-News/Japan-to-Overtake-China-As-Worlds-Top-LNG-Importer-This-Year.html
- Global LNG Hub: China LNG imports fall as supply mix shifts — https://globallnghub.com/china-lng-imports-fall-as-supply-mix-shifts/
- IEEFA: From buyer to broker: China’s emergence as a global LNG reseller — https://ieefa.org/resources/buyer-broker-chinas-emergence-global-lng-reseller
- Chinese customs / World Bank WITS trade data on 2025 LNG imports by partner
- CREA / Global Energy Monitor coal power reviews (2025–2026)
- Ember, National Bureau of Statistics, and related electricity generation statistics for 2025
- IGU World LNG Report and Kpler/ICIS forecasts cited across coverage
- Additional reporting on contracts (Venture Global/China Gas, etc.) and coal project proposals
All figures are subject to revision as final 2026 data become available.
The post Japan to Overtake China As World’s Top LNG Importer This Year appeared first on Energy News Beat.